We examine what rising conversion costs, mortgage conditions and licensing requirements mean for property investors.
HMO conversion costs put investment profitability under pressure
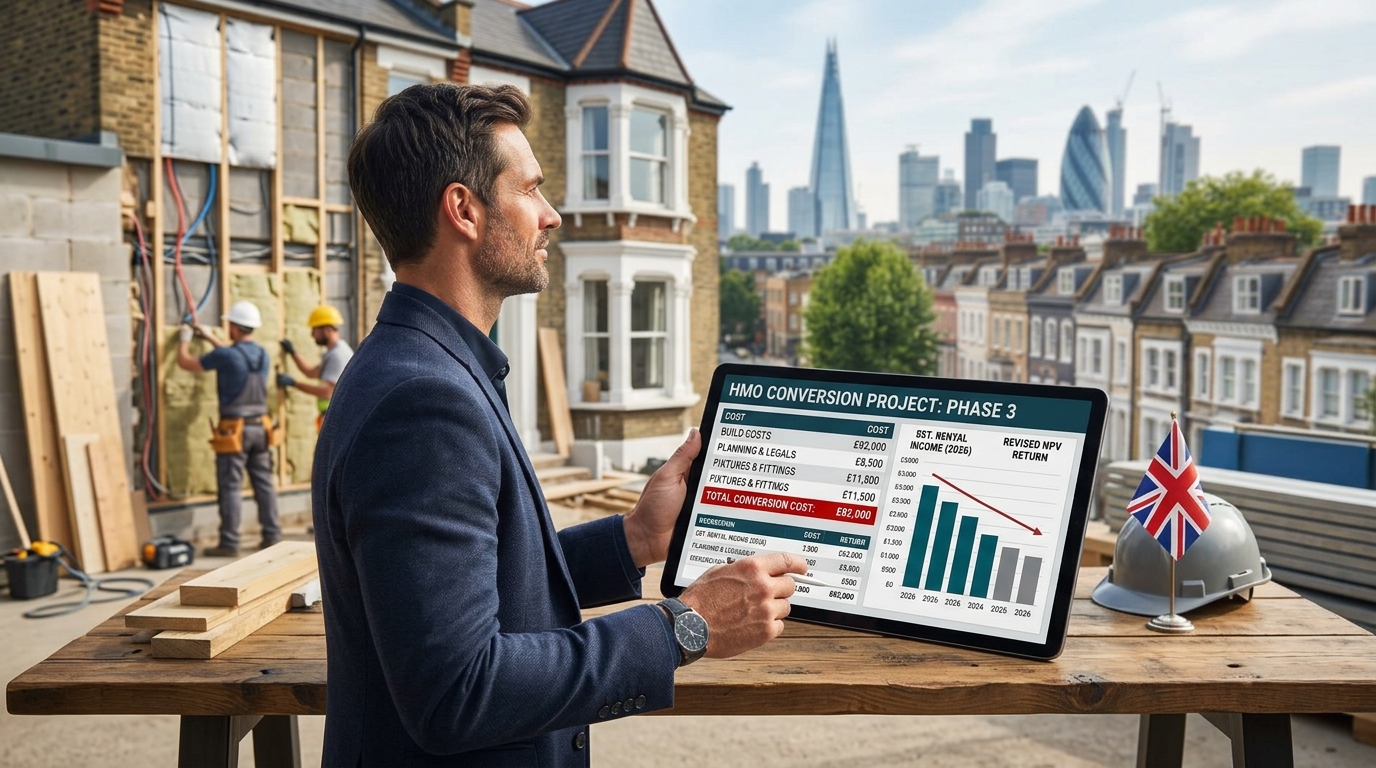
Property investors considering houses in multiple occupation (HMOs) face substantial upfront costs, with new research indicating that converting a residential property into an HMO costs an average of £82,084 across England.
Research from Rushbrook, reported on 15 October 2026, places the average conversion cost in London at approximately £92,796.
These figures come before the purchase price of the property itself.
The findings highlight the financial commitments involved in creating shared rental accommodation and raise important questions about the profitability of HMO investment in the current market.
Although HMOs can generate higher gross rental income than conventional single-family lettings, investors must consider conversion expenses, financing, licensing, management and ongoing maintenance before determining whether a project is financially viable.
What is an HMO?
A house in multiple occupation is generally a residential property occupied by people from more than one household who share facilities such as a kitchen, bathroom or toilet.
In England, a property is generally considered a large HMO for mandatory licensing purposes when it is occupied by five or more people forming more than one household and sharing facilities.
However, some local authorities operate additional licensing schemes covering smaller HMOs.
The rules also differ between England, Scotland, Wales and Northern Ireland.
For property investors, this means that understanding the local regulatory framework is essential before purchasing a property for conversion.
Why are HMO conversions expensive?
Converting an ordinary residential property into suitable shared accommodation often requires more than dividing existing rooms into bedrooms.
Depending on the property's condition, layout and local requirements, an investor may need to undertake extensive refurbishment.
Typical expenditure can include:
-
Fire detection and alarm systems
-
Fire-resistant doors
-
Emergency lighting where required
-
Electrical upgrades
-
Additional bathrooms
-
Kitchen improvements
-
Heating and ventilation
-
Plumbing modifications
-
Bedroom alterations
-
Sound insulation
-
Furniture and appliances
-
Building-control compliance
-
Planning and professional fees
Some properties may require significant structural changes.
Others may already have suitable layouts and require comparatively modest alterations.
Consequently, the national average should be treated as a benchmark rather than a quotation for any particular project.
How much money does an HMO investment require?
Consider an illustrative investment involving the purchase of a property for £250,000.
The investor plans to convert the property into a five-bedroom HMO.
The estimated costs might look like this:
| Expense | Illustrative amount |
|---|---|
| Property purchase | £250,000 |
| Conversion and refurbishment | £82,000 |
| Legal and professional expenses | £4,000 |
| Licensing and compliance allowance | £3,000 |
| Contingency reserve | £10,000 |
| Total estimated project cost | £349,000 |
These figures are illustrative and exclude purchase taxes and financing costs, which could be substantial.
They also assume that the proposed layout is legally permissible and that the conversion can be completed within the estimated budget.
The example demonstrates why investors should assess total project expenditure rather than focusing solely on the purchase price.
Can HMOs still generate attractive rental income?
HMOs can generate income from several individual tenancies.
For example, a five-bedroom HMO charging £650 per room each month could produce:
5 rooms × £650 = £3,250 monthly gross rent
That equals:
£3,250 × 12 = £39,000 annual gross rental income
Using the illustrative total project cost of £349,000:
Gross yield = (£39,000 ÷ £349,000) × 100
The resulting gross yield is approximately 11.2%.
This is a hypothetical calculation, not an estimate of typical HMO returns.
Actual rents depend on location, property condition, room size, tenant demand and included services.
More importantly, gross rental income is not the same as profit.
The hidden costs of HMO ownership
HMOs can be more expensive to operate than conventional buy-to-let properties.
A landlord may be responsible for utilities, broadband, communal-area cleaning and maintenance.
There may also be greater tenant turnover.
An investor should therefore account for:
Management costs: Managing multiple tenants can involve more administration and communication.
Utilities: Electricity, gas, water and internet may be included in room rents.
Maintenance: Shared kitchens, bathrooms and communal facilities can experience heavy use.
Insurance: Specialist HMO insurance may be required.
Licensing: Applicable licensing fees and renewal costs vary by local authority.
Void periods: Individual rooms may remain empty between tenancies.
Finance: Specialist HMO mortgages may carry different interest rates and fees from standard buy-to-let products.
A high gross yield can quickly become less attractive when these expenses are included.
Specialist HMO mortgage options are changing
There have also been developments in HMO financing.
On 15 October, specialist lender HTB announced an increase in its maximum HMO lending to 80% loan-to-value.
The change is intended to provide additional financing flexibility for qualifying borrowers.
Loan-to-value measures the size of a mortgage relative to the property's valuation.
For example, an 80% LTV mortgage on a property valued at £300,000 would represent borrowing of £240,000.
The investor would need to provide the remaining equity and cover relevant transaction costs.
However, maximum LTV does not mean every borrower will qualify for that level of borrowing.
Lenders also consider rental income, property characteristics, experience, creditworthiness and affordability requirements.
Why experienced landlords may have an advantage
HMO lending can involve more complicated underwriting than conventional residential property finance.
Lenders may assess:
-
Previous landlord experience
-
HMO management experience
-
Property valuation
-
Licensing status
-
Number of bedrooms
-
Expected rental income
-
Property location
-
Building condition
-
Exit strategy
Experienced landlords may be better positioned to demonstrate that they understand these risks.
Nevertheless, new investors can still explore suitable products, depending on lender criteria.
Planning permission and Article 4 restrictions
Financing is only one part of the process.
Investors must also establish whether the property can legally be converted into an HMO.
In some areas, Article 4 Directions remove permitted development rights that would otherwise allow certain changes from ordinary residential use to small HMO use without a planning application.
A current example is Stoke-on-Trent, where city-wide HMO planning controls are scheduled to take effect on 23 October 2026.
This demonstrates why investors should check local planning restrictions before committing to a purchase.
A property may appear financially attractive but prove unsuitable for the intended HMO use.
Student HMOs versus professional HMOs
Investors generally consider two broad tenant markets.
Student HMOs
Student accommodation can provide predictable demand near universities.
However, tenancy cycles may be linked to the academic calendar, and demand can vary between institutions and neighbourhoods.
Professional HMOs
Professional shared housing often targets working adults seeking affordable accommodation.
Demand may be influenced by employment opportunities, transport connections and local rental affordability.
Neither approach is automatically superior.
The best strategy depends on local demand and operating costs.
How should investors evaluate an HMO deal?
A thorough investment appraisal should include five essential questions.
1. Is there sufficient rental demand?
Investigate room rents, occupancy levels and competing properties.
2. Is the conversion legally feasible?
Check planning permission, licensing and building requirements.
3. What is the full project cost?
Include acquisition, refurbishment, finance, professional fees and contingency.
4. What is the realistic net income?
Deduct operating expenses, void allowances and financing costs.
5. Is the exit strategy credible?
Consider whether the property could be refinanced, sold as an HMO or returned to conventional residential use where legally possible.
Is HMO investment still worth considering in 2026?
HMO investment remains a potential strategy for landlords seeking stronger rental income.
However, the latest conversion-cost research reinforces the importance of careful financial planning.
An investor purchasing an inexpensive property may still face substantial refurbishment and compliance expenditure.
Similarly, access to higher-LTV mortgage products does not eliminate the risk of weak cash flow or unexpected construction costs.
The strongest opportunities are likely to be properties where the purchase price, conversion budget, achievable rent and financing structure work together.
Conclusion
The average £82,084 HMO conversion cost is an important reminder that shared accommodation investment requires substantial preparation.
At the same time, developments in specialist mortgage lending show that finance providers continue to serve the sector.
For investors, the question is not simply whether an HMO can generate more rent than a conventional buy-to-let.
It is whether the property can generate sustainable net income after the full cost of acquisition, conversion, financing, management and compliance.
That calculation should determine whether an HMO investment proceeds.
Related reading
-
What Is an HMO? A Beginner's Guide
-
HMO vs Buy-to-Let: Which Investment Strategy Is Better?
-
How to Calculate Rental Yield
-
HMO Licensing Requirements in the UK
-
How to Analyse a Property Investment Deal
Sources
Research reported by Residential Landlord and specialist lending developments reported by Property Reporter.
Disclaimer: This article is for general information and does not constitute financial, investment, mortgage or legal advice.

0 Comments
No comments yet. Be the first to share your thoughts.